Investors seeking protection against stock-market losses face a timely question: can seasonal easing offer reassurance after renewed hedging demand pushed the Cboe Volatility Index higher? VIX measures expected S&P 500 volatility.[1][5]
The approaching October 24–November 18, 2026 window includes the October Fed meeting. The same seasonal period ended with a lower VIX in all eight selected midterm years spanning 1994–2022, although broader histories were less consistent. That favorable record offers perspective on the recent rise without establishing that it will reverse.[5][4][1]
Protection demand and inflation
Cboe’s October 19 report said VIX rose five points over the preceding week to 20, “driven primarily by demand for downside convexity,” or protection against sharp losses. It also attributed steeper S&P 500 option skew to strong protection demand. Separately, Cboe said credit volatility rose “as investors repriced the debt-funded AI buildout,” across high-yield and investment-grade borrowers. It noted that interest-rate volatility held steady despite hotter-than-expected core CPI and headline PPI.[1]
BLS reported September consumer prices up 0.6% month over month, versus August’s 0.4%, on October 14. Its October 15 release put final-demand producer inflation at 1.3%, versus 0.5%. Both measures are seasonally adjusted.[2][3]
These observations neither establish conditions at the future October 24 entry nor validate a seasonal decline.[1][5]
September inflation readings
Reported seasonally adjusted monthly changes

View chart data & download
| Measure | Value | Period | Status |
|---|---|---|---|
| Consumer prices | 0.6 | September 2026 | reported |
| Final-demand producer prices | 1.3 | September 2026 | reported |
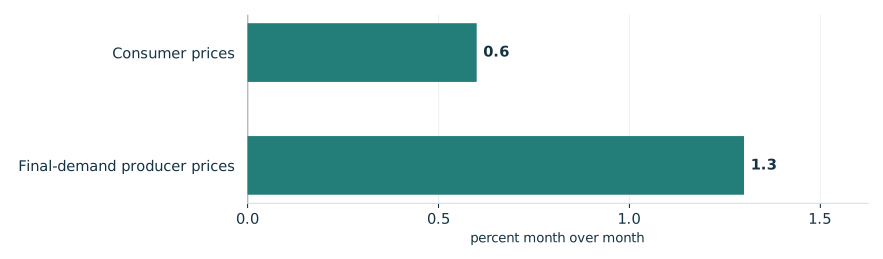
What the midterm record means
TradeWave’s selected seasonal record gives a median direction-adjusted index change of 15.09% for the complete 26-day window. Positive short-direction figures mean declining index levels; the chart shows the actual index movement. Spot VIX cannot be bought or shorted directly, so these figures do not establish attainable futures, options or exchange-traded-product profits.[5]
The year-by-year seasonal record

View exact TradeWave observations and download
| Window starting year | Ending price change | Highest from entry | Lowest from entry |
|---|---|---|---|
| 1994 | -5.72% | +5.30% | -16.32% |
| 1998 | -16.21% | +4.29% | -20.94% |
| 2002 | -18.72% | +0.00% | -22.30% |
| 2006 | -7.51% | +9.09% | -8.07% |
| 2010 | -5.54% | +16.22% | -10.18% |
| 2014 | -13.97% | +10.92% | -23.15% |
| 2018 | -20.33% | +10.42% | -36.23% |
| 2022 | -22.55% | +0.50% | -25.06% |
Explore this exact seasonal window in TradeWave. Compare its win rate and average result across different histories, and inspect how far prices moved above or below their starting point. Account access applies in TradeWave.
A lower finish can conceal a rise
The yearly range chart shows each year’s same seasonal period, not its whole calendar year. October 24–November 18, 2010 is useful because VIX finished 5.54% lower yet reached 16.22% above its starting level. The highs and lows reveal movement within the window that the ending result misses, without revealing their order or a peak-to-trough drawdown.[5]
What happened inside each seasonal window

View exact TradeWave observations and download
| Window starting year | Ending price change | Highest from entry | Lowest from entry |
|---|---|---|---|
| 1994 | -5.72% | +5.30% | -16.32% |
| 1998 | -16.21% | +4.29% | -20.94% |
| 2002 | -18.72% | +0.00% | -22.30% |
| 2006 | -7.51% | +9.09% | -8.07% |
| 2010 | -5.54% | +16.22% | -10.18% |
| 2014 | -13.97% | +10.92% | -23.15% |
| 2018 | -20.33% | +10.42% | -36.23% |
| 2022 | -22.55% | +0.50% | -25.06% |
Broader histories temper confidence
Checking across all years tests whether the eight selected midterms overstate consistency. Declines occurred in 80.0% of 2016–2025 windows and 75.0% of 2006–2025 windows, making reassurance less convincing when you look further back. Those comparisons reuse two and five primary-study years, respectively, limiting independent confirmation. The small selected sample and different historical periods cannot establish an election effect.[5]
See the history behind this comparison
TradeWave checks the same seasonal dates across different sets of years. This helps show whether the pattern holds up when you look at another stretch of history.
| History | Observed start years | Direction | Success rate | Median result |
|---|---|---|---|---|
| Article study: 8 selected midterm-election years (1994–2022) | 1994, 1998, 2002, 2006, 2010, 2014, 2018, 2022 | short | 100.0% | 15.09% |
| 10 consecutive historical windows (2016–2025) | 2016, 2017, 2018, 2019, 2020, 2021, 2022, 2023, 2024, 2025 | short | 80.0% | 13.73% |
| 20 consecutive historical windows (2006–2025) | 2006, 2007, 2008, 2009, 2010, 2011, 2012, 2013, 2014, 2015, 2016, 2017, 2018, 2019, 2020, 2021, 2022, 2023, 2024, 2025 | short | 75.0% | 8.32% |
Some years appear in more than one group, so agreement is not an independent test. A requested lookback can extend beyond available history; the observed years are listed above. Election-cycle groups use matching phases, not consecutive years. Results follow the direction shown: a positive short result means prices fell. Small samples and different market periods make the comparison less conclusive.
The Fed and the historical illustration
The October 27–28 Fed meeting is the next policy checkpoint; October CPI and PPI follow on November 10 and 13. The question is whether volatility eases as those decisions and reports arrive.[4][2][3]
Recorded VIX levels in the chart below end October 19, 2026. Its rescaled average seasonal path uses this article’s eight selected years over the next 60 weekdays, October 20, 2026–January 11, 2027, a separate horizon from the full study window. It illustrates historical shape, not future readings or a target. Inspect the same window across histories and its range of outcomes in TradeWave before assuming calm.[5]
Price history and the seasonal outlook

Explore this exact seasonal window in TradeWave. Compare its win rate and average result across different histories, and inspect how far prices moved above or below their starting point. Account access applies in TradeWave.
About this seasonal analysis
8 selected midterm-election years (1994–2022). The selected dates, years, direction, returns and ranges come from TradeWave. When a window boundary is a weekend or market holiday, TradeWave uses the next available trading session. SMN displays the returned results without recalculating them. A year label identifies the start of the historical window; a window can end in the following calendar year.
Green and red bars show the underlying adjusted-price movement. The range endpoints measure changes from the entry price, not a peak-to-trough loss. Historical results are before trading costs and do not guarantee future performance.
Sources & methodology
- Week of 10/19/2026: Scramble for Downside Hedges Fuels VIX Surge Ahead of MegaCap Earnings · 2026-10-19
- Consumer Price Index News Release · 2026-10-14
- Producer Price Index News Release · 2026-10-15
- The Fed - Meeting calendars and information · 2026-10-07
- TradeWave VIX seasonal evidence · 2026-10-20