NVIDIA investors face a practical question: how quickly can supply catch up with AI demand? On October 21, management described demand as extraordinary and capacity as the constraint.[2]
That uncertainty accompanies the approaching October 29–November 7, 2026 long window. All six selected midterm years finished higher, although broader histories include losses. How much weight should investors give that favorable timing record while assessing the business?[3]
Reported sales, prospective capacity
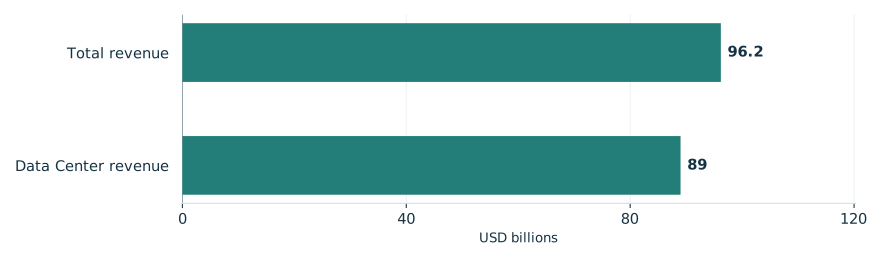
NVIDIA’s August 26 release reported $96.2 billion revenue, including $89.0 billion from Data Center, for fiscal Q2 ended July 26. Fiscal Q3 revenue guidance was $108.0 billion, plus or minus 2%, assuming no Data Center compute revenue from China.[1]
Both GAAP and non-GAAP gross margins were forecast at 74.0%, plus or minus 50 basis points, versus Q2’s 75.0%. Respective operating-expense forecasts were about $9.2 billion and $9.0 billion, versus $8.408 billion and $8.232 billion.[1]
The substrate plan targets a 2.5-fold capacity increase over three years. Samsung brings existing capacity, but wider substrate, packaging and testing expansions remain prospective.[2]
NVIDIA’s reported fiscal Q2 revenue
Quarter ended July 26, 2026; Data Center is part of total revenue

View chart data & download
| Measure | Value | Period | Status |
|---|---|---|---|
| Total revenue | 96.2 | Q2 FY2027 | reported |
| Data Center revenue | 89 | Q2 FY2027 | reported |
Six favorable midterm windows
TradeWave’s seasonal record covers six selected midterm-election years spanning 2002–2022. The 5.64% median full-window gain gives a more restrained perspective than the 12.02% all-window average; 2002 returned 36.36%. These are historical outcomes before costs.[3]
The year-by-year seasonal record

View exact TradeWave observations and download
| Window starting year | Ending price change | Highest from entry | Lowest from entry |
|---|---|---|---|
| 2002 | +36.36% | +54.77% | +0.00% |
| 2006 | +4.06% | +6.40% | -3.82% |
| 2010 | +5.31% | +6.24% | -0.65% |
| 2014 | +5.24% | +10.00% | -1.90% |
| 2018 | +15.18% | +19.60% | -0.00% |
| 2022 | +5.96% | +6.78% | -4.01% |
Explore this exact seasonal window in TradeWave. Compare its win rate and average result across different histories, and inspect how far prices moved above or below their starting point. Account access applies in TradeWave.
A winning finish can conceal discomfort
The yearly range chart shows each year’s same seasonal period, not the whole year. The latest selected example, October 29–November 7, 2022, illustrates the distinction: shares finished up 5.96% but traded 4.01% below the starting price. Its highs and lows do not reveal their order or a peak-to-trough drawdown.[3]
What happened inside each seasonal window

View exact TradeWave observations and download
| Window starting year | Ending price change | Highest from entry | Lowest from entry |
|---|---|---|---|
| 2002 | +36.36% | +54.77% | +0.00% |
| 2006 | +4.06% | +6.40% | -3.82% |
| 2010 | +5.31% | +6.24% | -0.65% |
| 2014 | +5.24% | +10.00% | -1.90% |
| 2018 | +15.18% | +19.60% | -0.00% |
| 2022 | +5.96% | +6.78% | -4.01% |
Broader histories temper the perfect score
Checking across all years tests whether the favorable reading extends beyond midterms: 2016–2025 had 90.0% profitable windows, versus 85.0% for 2006–2025. Neither supports certainty from six observations. The shorter history reuses 2018 and 2022; the longer reuses every selected year except 2002, limiting independent confirmation.[3]
See the history behind this comparison
TradeWave checks the same seasonal dates across different sets of years. This helps show whether the pattern holds up when you look at another stretch of history.
| History | Observed start years | Direction | Success rate | Median result |
|---|---|---|---|---|
| Article study: 6 selected midterm-election years (2002–2022) | 2002, 2006, 2010, 2014, 2018, 2022 | long | 100.0% | 5.64% |
| 10 consecutive historical windows (2016–2025) | 2016, 2017, 2018, 2019, 2020, 2021, 2022, 2023, 2024, 2025 | long | 90.0% | 5.03% |
| 20 consecutive historical windows (2006–2025) | 2006, 2007, 2008, 2009, 2010, 2011, 2012, 2013, 2014, 2015, 2016, 2017, 2018, 2019, 2020, 2021, 2022, 2023, 2024, 2025 | long | 85.0% | 5.3% |
Some years appear in more than one group, so agreement is not an independent test. A requested lookback can extend beyond available history; the observed years are listed above. Election-cycle groups use matching phases, not consecutive years. Results follow the direction shown: a positive short result means prices fell. Small samples and different market periods make the comparison less conclusive.
What to inspect before entry
Recorded prices end October 23, 2026, and cannot establish October 29’s starting conditions. The chart below places TradeWave’s normalized seasonal overlay from this article’s selected years on the price chart. Its next 60 weekdays, October 26, 2026–January 15, 2027, are a separate illustration horizon from the full seasonal window, not future recorded prices or a forecast. Before entry, inspect the same window’s individual outcomes and ranges in TradeWave.[3]
Price history and the seasonal outlook

Explore this exact seasonal window in TradeWave. Compare its win rate and average result across different histories, and inspect how far prices moved above or below their starting point. Account access applies in TradeWave.
About this seasonal analysis
6 selected midterm-election years (2002–2022). The selected dates, years, direction, returns and ranges come from TradeWave. When a window boundary is a weekend or market holiday, TradeWave uses the next available trading session. SMN displays the returned results without recalculating them. A year label identifies the start of the historical window; a window can end in the following calendar year.
Green and red bars show the underlying adjusted-price movement. The range endpoints measure changes from the entry price, not a peak-to-trough loss. Historical results are before trading costs and do not guarantee future performance.